
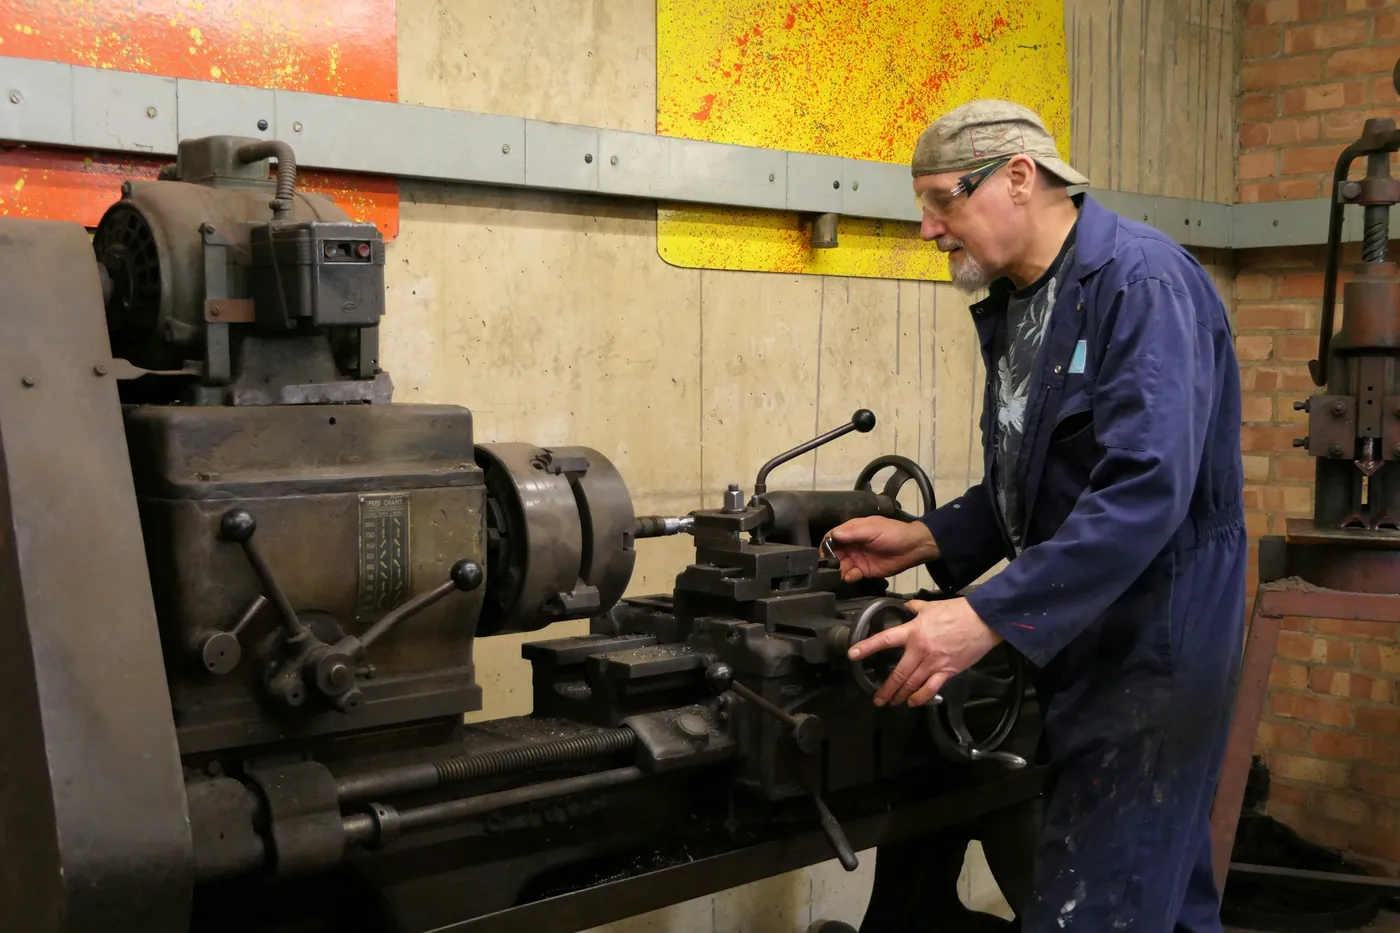
Finance for buying equipment in manufacturing

Production machinery is the largest purchase most manufacturers make, so the finance has to be judged against output, not just price.

  • Our form won’t affect your credit score
  • £5,000 to £2m+ for UK limited companies and LLPs
  • Free to use, no obligation
Free to useNo fees for businesses, ever
About a minuteOne short form, plain English
Specialist brokersMatched to your type of finance
Your data protectedOnly shared with your consent

The basics

Machinery is how a manufacturer makes money, and it is the biggest single outlay in most workshops. A five-axis CNC machine, a laser cutter, an injection moulding press, a packaging line or a paint booth can each cost from £50,000 to well over £500,000. Machines also come with extras such as tooling, installation, software and training, which a finance quote should ideally cover. Spreading the cost over the years a machine produces is how most manufacturers keep cash free for materials and wages, and for the next order.

Asset finance is the established route. Hire purchase suits a machine the factory will keep for ten years, while leasing can suit equipment that needs replacing sooner. Because machinery is easy to value and often resalable, lenders can often arrange it more readily than an unsecured loan of the same size. A broker will look at how the machine improves capacity, scrap rates or margin, because that is the case lenders want to see.

What businesses use it for

A new CNC or laser cutter

A fabricator buys a machine that can take on work currently outsourced, financing it over five to seven years so payments sit below the margin the extra work earns.

A production line upgrade

A food or packaging manufacturer replaces a line to raise output or meet a customer’s new specification, often as a staged purchase.

Tooling and moulds

A plastics business finances new moulds for a customer contract, with the term matched to the length of that contract rather than the machine’s life.

Refinancing existing machinery

A manufacturer that owns equipment outright raises cash against it through asset refinance, keeping production running while releasing money for a different part of the business.

How it fits

Typical amounts and terms

Mid-range machines are often £30,000 to £250,000, with large lines and presses higher. Terms commonly run from three to seven years, longer for heavy plant with a long working life, and lenders usually ask for a deposit that varies with the machine and your accounts.

What lenders look at

They look at the company’s accounts, order book and key customers, because a machine that depends on one contract is riskier. They also look at resale value: widely used makes from known suppliers are easier to finance than one-off or highly customised machines.

Installation and staged payments

Large machines are delivered and commissioned over weeks or months. Some lenders support staged drawdown or pre-delivery payments to the supplier, which matters when a manufacturer is paying for a machine that is not yet producing.

What could it cost each month?

An illustration only. The rate you’re offered depends on the lender and your business.

Open the full calculator
Monthly repayment£0
Show breakdown
Amount borrowed
Interest
Total repayable
Get matched with a broker

Get matched without affecting your credit score

  1. 1

    Tell us what you need

    One short form about your business and the loan. It takes about a minute and won’t affect your credit score.

  2. 2

    We match you

    We pick a specialist broker who arranges this type of finance for businesses like yours.

  3. 3

    The broker calls you

    They talk through your options and approach lenders that fit your circumstances.

  4. 4

    You decide

    Compare any offers. There’s no obligation to go ahead, and Loanleaf is free to use.

Things to consider

Customisation and resale value

The more a machine is built to a unique specification, the less a lender can get if it has to be sold. Expect lower advances or larger deposits for bespoke equipment.

Downtime and commissioning

A machine that is delayed or slow to reach full output still carries payments. Build a buffer into your plans for installation, training and ramp-up before the new output covers the cost.

When it is not the right fit

If cash is tied up in raw materials or slow-paying customers rather than machinery, invoice finance or a revolving credit facility addresses the cause more directly. A broker can advise how to separate those needs.

Questions and answers

How do lenders value specialist machinery?
They look at the make and model, age, condition and how easily a similar machine can be sold. Common brands with an active used market are easier than one-off builds. Lenders may ask for a supplier invoice, specifications and sometimes an independent valuation. A broker can tell you how lenders view the particular equipment.
Can I finance machinery from an overseas supplier?
Often yes, though it can require extra checks on the supplier, the currency and import costs. Some lenders will pay the supplier directly, and some will include delivery and installation in the amount financed. Bring the quote and shipping terms to the broker early, as the structure can affect timing.
What is asset refinance?
It lets a company that already owns equipment raise cash against it, usually by selling it to a lender and leasing it back, or borrowing against its value. It can release money for other uses, but you pay interest and take on a new commitment. A broker can explain whether it suits your situation.
Is hire purchase or leasing better for factory equipment?
Hire purchase suits machines you will run for years, because you usually own them at the end. Leasing can suit equipment that may be upgraded, with payments treated differently for tax and VAT. The right choice depends on your accounting and plans, so ask your accountant before agreeing.
Can a manufacturer finance software and installation as well?
Sometimes. Many lenders will include delivery, installation and basic software with the machine in a single agreement, provided these are on the supplier’s invoice. Large or separate software licences can be harder to finance. A broker can say which costs a particular lender is willing to include.
How can Loanleaf help?
Loanleaf is an introduction service, not a lender or broker, and we don’t give advice. You answer one short form about your company and what you need, and we match you with a specialist finance broker who works with manufacturing businesses looking at buying equipment. It’s free to use and there’s no obligation to go ahead. The broker will explain any fees of their own.
Ready to see your options?
One short form. A specialist broker calls you.
Get a quote